Home › Free tools › s455 calculator
s455 calculator
If you owe your company money at the end of its year and don’t pay it back within 9 months, the company pays s455 tax on it. See how much, and the dates that matter. Nothing you type leaves your device.
How s455 works
- s455 applies when a shareholder of a close company (most small companies) owes the company money at the end of its accounting period.
- If the loan isn’t repaid, written off or cleared within 9 months of the year end, the company pays s455 on what’s still owed, 9 months and 1 day after the year end.
- The rate is 33.75% on loans made before 6 April 2026 and 35.75% on loans made from 6 April 2026.
- The company gets the tax back once the loan is repaid, 9 months and 1 day after the end of the accounting period in which it’s repaid.
- Loans over £10,000 can mean a benefit in kind and need shareholders’ approval.
Example: a company with a 31 March 2027 year end has until 31 December 2027 to clear the loan. If £8,000 borrowed in 2026 is still owed then, the company pays £8,000 × 35.75% = £2,860 on 1 January 2028.
Read our guide to director’s loan accounts. Sources: CTM61505 and Director’s loans on GOV.UK.
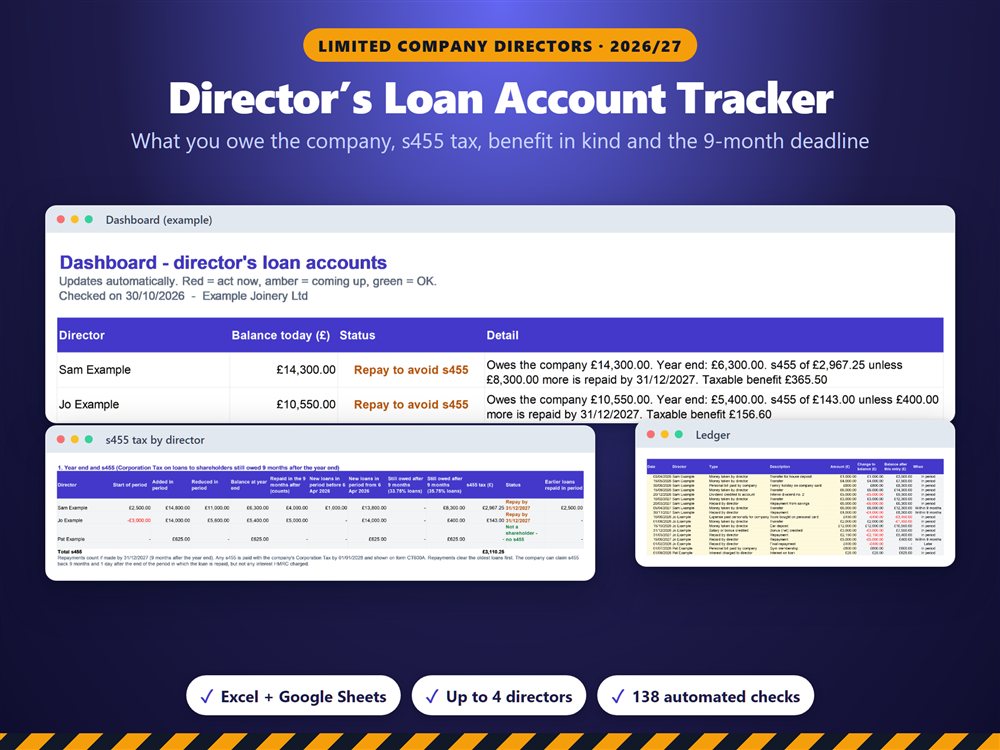
Director’s Loan Account Tracker
A running balance for up to 4 directors, the s455 split between the 33.75% and 35.75% rates, benefit in kind on loans over £10,000, and a flag for the 30-day rule.
Director’s loan tracker on Etsy