Home › Directors › Director’s loan accounts
Director’s loan accounts and s455 tax: the 2026 rules
If you take money out of your company that isn’t salary, a dividend or an expense being repaid, you have a director’s loan. It’s allowed, but leave it unpaid too long and the company pays extra tax — and from 6 April 2026 that tax went up.
The short version
- Your director’s loan account records money you take out of the company, and money you put in, that isn’t salary, dividends or expense repayments.
- If you owe the company money at the end of its accounting period and haven’t repaid it 9 months and 1 day later, the company pays s455 tax on what’s still owed.
- The rate is 33.75% on loans made before 6 April 2026 and 35.75% on loans made from then.
- The company gets the s455 back once the loan is repaid, but not straight away.
- Over £10,000, there’s a benefit in kind to report and the loan needs shareholders’ approval.
What counts as a director’s loan
Anything the company pays to you, or for you, that isn’t salary, a properly declared dividend, or repayment of money you’ve spent on the company. Common examples:
- transfers from the business account to your personal account “on account”;
- personal bills paid with the company card;
- “dividends” taken when there weren’t enough profits to declare them.
Money you put into the company, salary or dividends credited to your account rather than paid out, and expenses you paid personally all go the other way. If the account is in credit, the company owes you and there’s no s455 to worry about.
s455 tax and the 9-month deadline
If you’re a shareholder (a “participator” in a close company, which covers most small companies) and you owe the company money at the end of its accounting period, the company must pay s455 tax on whatever is still unpaid 9 months and 1 day after the period ends. It goes on form CT600A with the Company Tax Return.
So a company with a 31 March 2027 year end has until 31 December 2027 for the loan to be repaid, written off or cleared with a dividend or bonus. Clear it in time and there’s no s455 at all.
s455 isn’t a cost to you personally: it’s a temporary tax on the company, a bit like a deposit.
The new 35.75% rate
The s455 rate follows the higher dividend tax rate. From 6 April 2026 the higher rate went up to 35.75%, so s455 on loans made on or after 6 April 2026 is 35.75%. Loans made before that date stay at 33.75%.
A company with an accounting period that spans April 2026 can have loans at both rates. HMRC’s guidance treats repayments as clearing the oldest loans first. HMRC has also said its Corporation Tax online service won’t switch to the new rate until 6 April 2027, so returns filed before then may need to be amended.
| Loan made | s455 rate |
|---|---|
| Before 6 April 2026 | 33.75% |
| On or after 6 April 2026 | 35.75% |
Getting the tax back
Once the loan is repaid, released or written off, the company can reclaim the s455. The relief isn’t immediate: it’s due 9 months and 1 day after the end of the accounting period in which the loan was repaid. Claims must be made within 4 years. If the repayment falls in the same return period you can claim on CT600A; for older periods you claim separately.
Writing a loan off brings its own tax: it’s usually treated as income for the director, and there may be National Insurance.
The 30-day rule
Repaying a loan just before the deadline and borrowing the money straight back doesn’t work. If you repay £5,000 or more and take out new loans of £5,000 or more within 30 days, the repayment is matched to the new borrowing instead of the old loan. A similar rule catches arrangements to borrow again where the loan is £15,000 or more, even outside 30 days.
Repaying by declaring a dividend or bonus that’s credited to your account isn’t caught, because that’s income you pay tax on.
Loans over £10,000
Two extra rules kick in:
- Benefit in kind. If the loan is more than £10,000 at any point in the tax year and you pay less than HMRC’s official rate of interest (3.75% for 2026/27), the difference is a taxable benefit. It goes on a P11D by 6 July after the tax year, and the company pays Class 1A National Insurance at 15% by 22 July (19 July by post).
- Shareholders’ approval. Under the Companies Act 2006 (sections 197 and 207), loans to a director of more than £10,000 in total need the members’ approval before they’re made. With a written resolution, a memorandum setting out the nature of the loan, the amount, its purpose and the company’s liability must go to every shareholder. This doesn’t apply to a wholly-owned subsidiary.
Keeping the records
Keep a running ledger of every payment out and in, by director, with dates. Your accountant needs the balance at the year end, and you need to know what’s owed before the 9-month deadline. Agree any loan over £10,000 in writing, and keep the shareholders’ resolution with your minutes.
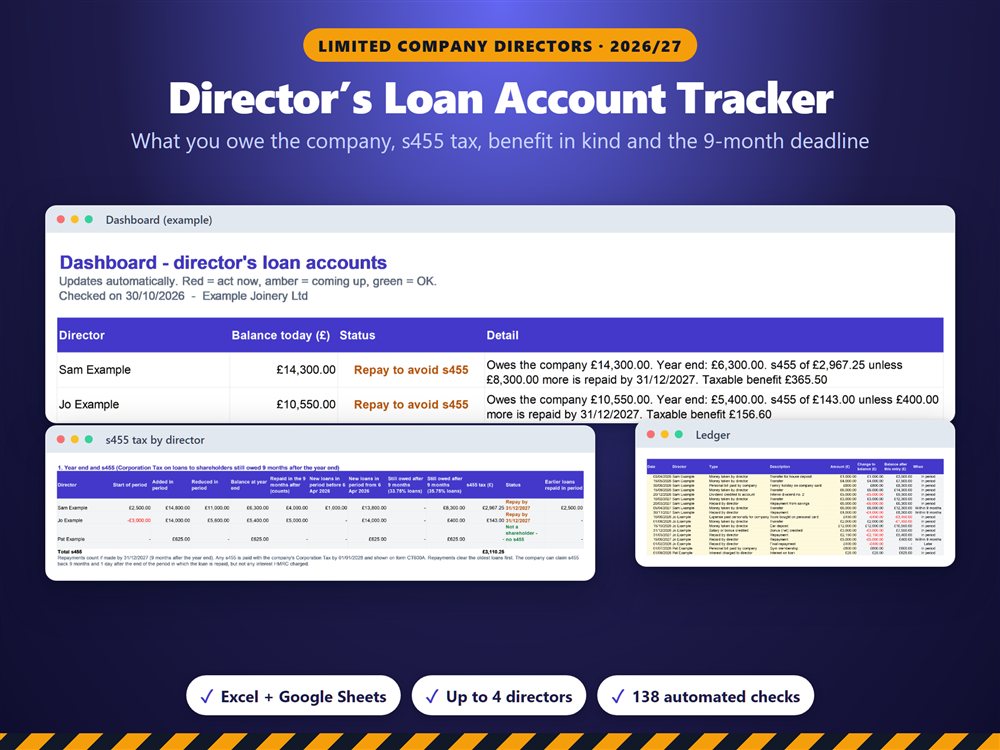
Log every payment for up to four directors. It works out s455 at 33.75% and 35.75%, the date tax becomes reclaimable, flags the 30-day rule, and calculates the benefit in kind and Class 1A on loans over £10,000. Our Company Minutes & Resolutions Pack includes the shareholders’ resolution and memorandum for approving a loan.
Loan tracker on Etsy Minutes pack on Etsy